Influencer Marketing Trends for 2027, With the Japan Numbers Global Reports Leave Out
- 1. The Short Version: Nine Trends for 2027
- 2. How We Built This Forecast
- 3. Trends 1-3: How People Find Things Is Changing
- 3-1. Trend 1: AI Search Becomes a Discovery Channel
- 3-2. Trend 2: Search Behavior Splits by Platform
- 3-3. Trend 3: Short Video Is No Longer a Trend, It Is the Format
- 4. Trends 4-6: How Brands Buy Is Changing
- 4-1. Trend 4: From One-Off Posts to Year-Long Ambassadors
- 4-2. Trend 5: Creator Content Becomes Ad Inventory
- 4-3. Trend 6: Measurement Moves Beyond the Click
- 5. Trends 7-9: What Regulation and Technology Force
- 5-1. Trend 7: Disclosure Rules Get Stricter, and Enforced
- 5-2. Trend 8: Nano Creators Become Operational, Not Experimental
- 5-3. Trend 9: Virtual Influencers Move From Demo to Deployment
- 6. What Japan Does Differently
- 6-1. Talent Agencies Still Sit Between You and the Creator
- 6-2. The Advertiser Carries the Disclosure Liability
- 6-3. Japanese Buyers Verify Before They Purchase
- 6-4. A Different Platform Mix: LINE and X
- 7. What Is Not Changing
- 7-1. Fit Still Beats Follower Count
- 7-2. Relationships Still Take Time to Build
- 7-3. Creative Quality Still Decides the Outcome
- 8. What to Put in Your 2027 Plan
- 9. FAQ
- 9-1. What are the biggest influencer marketing trends for 2027?
- 9-2. Is influencer marketing still growing?
- 9-3. How is AI changing influencer marketing?
- 9-4. Are influencer marketing costs going up?
- 9-5. What is different about influencer marketing in Japan?
- 9-6. Should brands move to long-term ambassador deals?
- 9-7. Will virtual influencers replace human creators?
- 10. Methodology and Data Sources
Pricing, past campaigns, and how contracts and ad-disclosure compliance are handled from start to finish. Ask us anything before you commit to a budget.
Overseas brands welcome. We work in English, Japanese, Chinese, and Korean.TL;DR: The biggest change in 2027 is that AI search becomes a front door for product discovery. Japan is heading the same way, more slowly where the data can show it, so a global playbook copied unchanged tends to arrive early. Three things are not changing: agency-managed creators, advertiser liability for disclosure, and fit over follower count.
Most influencer marketing trend reports describe the United States and Europe, few show where their numbers come from, and almost none mention Japan. This one lists nine trends for 2027, labels each as observed or forecast with its data, then turns the list into a plan for Japan and covers what is not changing. For the wider context, start with our guide to influencer marketing in Japan.
The Short Version: Nine Trends for 2027
All nine influencer marketing trends for 2027 at a glance; the sections below give the evidence and what to change.
| # | Trend | Label | Key data | Speed in Japan |
|---|---|---|---|---|
| 1 | AI search becomes a discovery channel | Observed | Generative AI traffic to US retail sites up 693.4%, Nov to Dec 2025 (Adobe) | Slower |
| 2 | Search behavior splits by platform | Observed in Japan | 25.76% of Japanese Instagram users and 21.11% of TikTok users use the apps to search for products (hotice, 2026) | Same |
| 3 | Short video is the format, not the trend | Observed | Online video ad spend in Japan passed 1 trillion yen in 2025, up 21.8% (Dentsu et al.) | Same |
| 4 | From one-off posts to year-long ambassadors | Observed | 91% of brands surveyed run always-on creator programs (Medill, June 2026) | Different |
| 5 | Creator content becomes ad inventory | Observed | Meta’s partnership ads revenue run rate more than doubled to $10 billion (Q1 2026) | Different |
| 6 | Measurement moves beyond the click | Forecast | US Google users clicked a result on 8% of visits with an AI summary, 15% without (Pew, 2025) | Same |
| 7 | Disclosure rules get stricter, and enforced | Observed | Only 20% of 576 influencers checked in the EU disclosed ads systematically (2024) | Different |
| 8 | Nano creators become operational | Forecast | 51.43% of marketers plan to expand their use of nano creators (Influencer Marketing Hub, 2026) | Same |
| 9 | Virtual influencers move to deployment | Forecast | 57.1% of Japanese users surveyed had no particular concern about influencers using AI-generated content (hotice, 2025) | Different |
If you only have time for three, read Trends 1, 4 and 7. They change where customers find you, how you contract creators, and what you are legally exposed to.
How We Built This Forecast
Every trend carries one of two labels, and every number names its source and date.
- Observed: published data from a named source already shows the change. The question for 2027 is how far it goes.
- Forecast: our judgement of where the observed data points. Every forecast names its data; candidate trends without data were dropped.
The “Speed in Japan” column is our judgement too. Only Trend 1 has a like-for-like comparison of Japan and other countries; the other ratings rest on how the Japanese market works today.
| Data | Type | Sample and timing | Used for |
|---|---|---|---|
| hotice Instagram and TikTok usage surveys | Own survey | 534 and 528 respondents in Japan; published February 2026 | Trend 2 |
| hotice Instagram and TikTok purchasing surveys | Own survey | 636 and 631 users (432 and 400 buyers); published February 2026 | Trends 3 and 6, Japan section |
| hotice survey on AI-generated content | Own survey | 149 social media users in Japan; published September 2025 | Trend 9 |
| MIC media usage survey and 2026 White Paper | Public statistics | 1,800 people (December 2025); 1,236 people (early 2026) | Trend 1, Japan section |
| Dentsu, CyberBuzz and Digital InFact | Industry estimates | Published November 2024 to March 2026 | Trends 3 and 5 |
| Adobe, Pew, IAB, Medill, Influencer Marketing Hub, Meta, EU, FTC, CAA | Third-party and regulatory | Listed in the methodology section | Trends 1 and 4 to 9 |
For Japanese market size by year and the full set of supporting numbers, see our influencer marketing statistics for Japan.
Trends 1-3: How People Find Things Is Changing
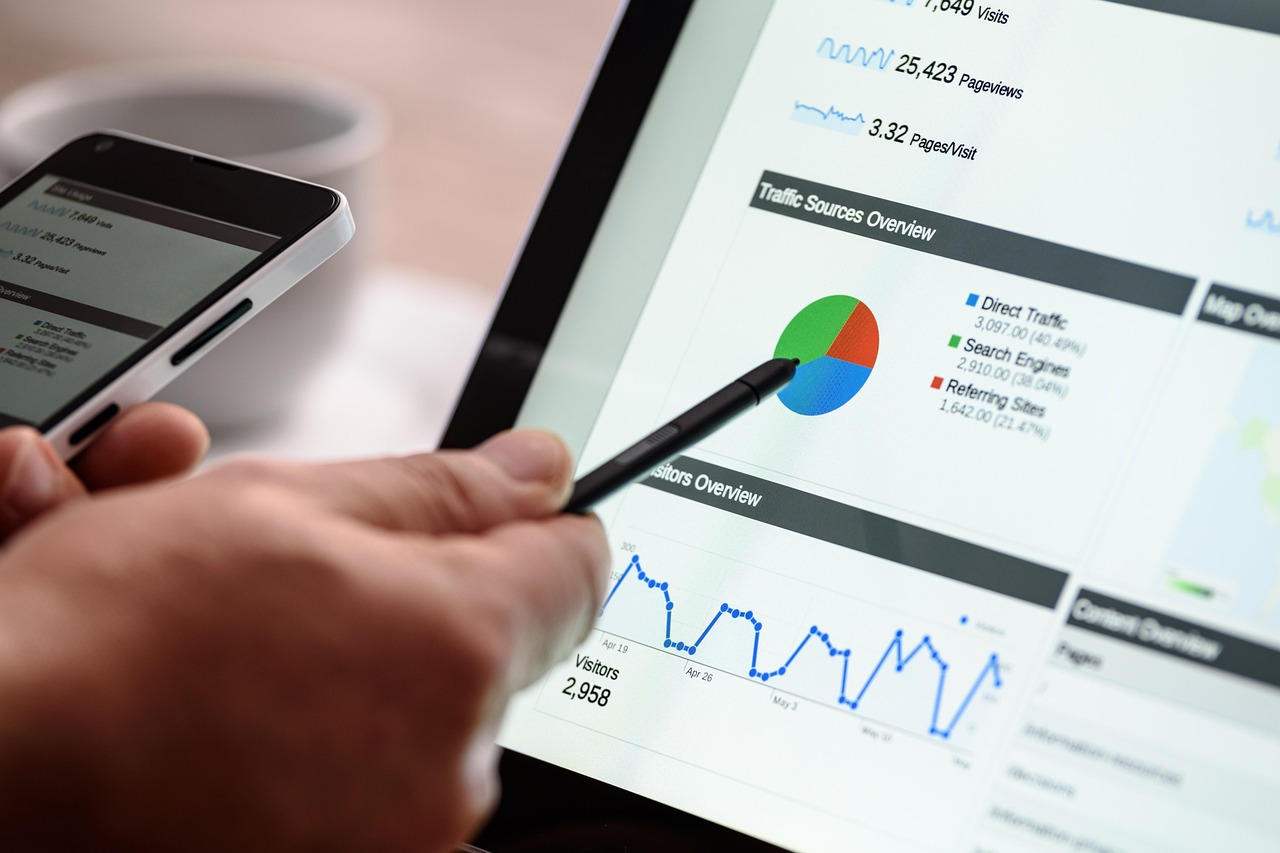
The future of influencer marketing starts with discovery: where people first meet a product decides which creators, formats and platforms are worth paying for.
Trend 1: AI Search Becomes a Discovery Channel
Label: Observed. Generative AI tools now send measurable shopping traffic. Adobe reported that traffic from generative AI tools to US retail sites rose 693.4% year on year between 1 November and 31 December 2025, while noting that the base of users is still modest. AI answers are also taking clicks from classic results: in Pew Research Center’s March 2025 browsing data for 900 US adults, Google users clicked a traditional search result on 8% of visits when an AI summary appeared, against 15% of visits when none did.
Japan is on the same path at a lower level. Google began rolling out AI Mode in Japanese on 9 September 2025. In the Ministry of Internal Affairs and Communications (MIC) 2026 White Paper, 58.8% of respondents in Japan had used a generative AI service, against 75.6% in both the United States and Germany. On a like-for-like basis (adults aged 20 and over), Japanese use rose from 26.7% to 52.2% in a year.
Our forecast is that in 2027 AI assistants become a routine first stop for product research in Japan too, and creator content becomes source material for their answers. In our view, three things make a page easier to cite: data in tables, a named source and date for every number, and headings written as the questions buyers ask. What to change: treat your Japanese product pages and the creator content around them as material an AI will quote, and structure them that way.
Trend 2: Search Behavior Splits by Platform
Label: Observed in Japan. In our January 2026 survey of Instagram users in Japan, 25.76% said they open the app to search for or consider products and services, and in our TikTok usage survey the figure was 21.11%. Among people who had bought something they found on Instagram, 28.94% looked for other users’ reviews through hashtags, rising to 39.39% among people in their twenties.
The platform where a product is found is often not where it is checked, so every surface needs to show the same product under the same name. Our guide to TikTok in Japan covers how that platform fits into the path. What to change: brief Japanese creators on the exact product name and category terms people search for, and ask for them in captions, on-screen text and hashtags.
Trend 3: Short Video Is No Longer a Trend, It Is the Format
Label: Observed. Short video is no longer something to test. In Japan, online video advertising reached 1,027.5 billion yen in 2025, up 21.8% and above one trillion yen for the first time, according to an analysis of Dentsu’s ad spend data by Dentsu, Dentsu Digital, CARTA Holdings and Septeni; Dentsu credits vertical video ads on social platforms with driving online ad growth. CyberBuzz and Digital InFact estimated influencer marketing built on vertical short video at 24.6 billion yen in 2024 and forecast 63.6 billion yen for 2029. Globally, YouTube says Shorts now averages 200 billion daily views.
It also sells: in our Instagram purchasing survey, 37.04% of buyers named videos under one minute that summarise a product’s appeal as a deciding factor. Our forecast is that the 2027 question is sequencing, not format: short clips create interest, and longer reviews, livestreams or product pages carry viewers through the checking Japanese buyers do before paying. What to change: plan short and long content as one sequence, and brief creators on which job each piece does.
Trends 4-6: How Brands Buy Is Changing
These influencer marketing predictions for 2027 are about the buyer’s side: brands are signing creators for longer, reusing their content as ads and judging results on more than clicks.
Trend 4: From One-Off Posts to Year-Long Ambassadors
Label: Observed. In the Medill Spiegel Research Center’s creator marketing study, fielded in June 2026 among 209 senior marketing decision-makers, 91% of brands ran a creator program with an always-on component: 62% a hybrid of campaigns and continuous work, and 29% fully continuous. The study does not say where respondents are based.
The appeal: repeated mentions over a year read less like an advert than a single post, and a creator who has used the product for months has more to say. In Japan, a year-long ambassador deal is usually a contract with the creator’s agency (see the Japan section below). What to change: put your core creators on annual terms and negotiate exclusivity and usage rights at the start, not post by post.
Trend 5: Creator Content Becomes Ad Inventory
Label: Observed. On its Q1 2026 earnings call, Meta said the revenue run rate of its partnership ads, which run creator content as paid media, had more than doubled year on year to $10 billion. In the Medill study, 92% of brands ran creator content in social advertising, and 73% put between 11% and 40% of their influencer budget into boosting it. In Japan, social advertising reached 1,306.7 billion yen in 2025, up 18.7% and equal to 39.5% of internet ad media spend, according to the same analysis.
Secondary use changes how a creator deal is priced. Paid usage, its duration, the channels it runs on and permission to advertise from the creator’s account are negotiated separately from the post itself. See our breakdown of influencer marketing costs in Japan and our guide to influencer contracts in Japan. What to change: agree paid usage, period and channels in the creator contract before the post goes live.
Trend 6: Measurement Moves Beyond the Click
Label: Forecast. Click-based attribution is weakening for three reasons. AI answers reduce clicks (see Trend 1). Browsers limit tracking: Safari has blocked third-party cookies by default since March 2020, so even after Google decided in April 2025 to keep them in Chrome, cookie-based tracking misses part of every audience. And in Japan, since 16 June 2023, amended rules under the Telecommunications Business Act have required many websites and apps to tell users what data their tags send to third parties.
Meanwhile, the sale often happens away from the post: many Japanese buyers search for the product and check retailers before paying (see the Japan section below), so a working campaign can show up as branded search, saves and retail sales rather than clicks. Measurement practice is still mixed: in the Medill study, 51% of brands reported on awareness and 51% on campaign sales, and only 30% used data-driven attribution.
Our forecast is that in 2027 more creator programs will be judged on saves, branded search lift and retail or in-store sales. What to change: record a baseline for branded search and saves before each campaign starts, and report against it.
Trends 7-9: What Regulation and Technology Force
Trend 7 is imposed by regulators whether a brand plans for it or not. Trends 8 and 9 are forecasts about what brands will make routine.
Trend 7: Disclosure Rules Get Stricter, and Enforced
Label: Observed. Since 1 October 2023, stealth marketing has been a violation of Japan’s Act against Unjustifiable Premiums and Misleading Representations, and in Japan the legal responsibility for disclosure sits with the advertiser, not the creator. The Consumer Affairs Agency (CAA) issued its first order under the rule in June 2024 and has kept going: its enforcement summary for the year to 31 July 2026 includes a June 2026 order against a company that recruited people, gave them free products, asked them to post on social media, then showed excerpts of those posts on its own site without making clear they were its advertising. See our guide to Japan’s stealth marketing regulation.
In the United States, the Federal Trade Commission’s rule on consumer reviews and testimonials took effect in October 2024; it bans knowingly buying fake indicators of social media influence such as bot followers, and in December 2025 FTC staff sent warning letters to 10 companies under it. In the European Union, a sweep of 576 influencers by the Commission and national authorities, published in February 2024, found that 97% posted commercial content but only 20% systematically disclosed it as advertising. What to change: add a disclosure check to every approval step, including when creator content is reused on your own site or in ads.
Trend 8: Nano Creators Become Operational, Not Experimental
Label: Forecast. Marketers plan to lean further into small creators. In Influencer Marketing Hub’s 2026 benchmark report, based on more than 600 respondents, 51.43% said they planned to expand their use of nano creators and 52.83% micro creators, while macro plans were evenly split. The report does not publish its follower thresholds; on our statistics page, nano means 1,000 to 10,000 followers and micro 10,000 to 100,000.
Fifty nano creators is an operations job, not a casting job. Our forecast is that in 2027 the brands that scale it will have a repeatable system for shipping, standard briefs and contracts, and disclosure checks, run in-house or through a partner. What to change: budget for the operational work of a nano program, not only for creator fees.
Trend 9: Virtual Influencers Move From Demo to Deployment
Label: Forecast, with the thinnest evidence of the nine. A VTuber is a performer behind an animated avatar, and in Japan VTubers are already mainstream: Yano Research Institute estimated the market at 105 billion yen in FY2024 and forecast 126 billion yen for FY2025. A virtual influencer is a produced persona with no live performer, usually owned by a company. Our guide to VTuber marketing in Japan covers the first group.
Virtual influencers have no Japanese market figure, only an indirect signal of audience tolerance. In our September 2025 survey of 149 Japanese social media users, 57.1% said they had no particular concern about influencers using AI-generated content, 23.8% felt favourable and 19.1% felt distrust. The question was about AI content, not virtual personas, and the sample is small, so read it as direction only. Our forecast is that brands will deploy owned virtual characters as always-on spokespeople alongside human creators, not in place of them. What to change: if you test a virtual influencer, label it clearly as virtual and keep human creators for reviews and first-hand use.
What Japan Does Differently
Everything above is the global picture. From here on, this is about Japan, the part global reports leave out. The same trends arrive, filtered through four local differences.
hotice is a cross-border influencer marketing agency helping overseas brands enter Japan. We handle casting, negotiation, Japanese-language contracts, and ad-disclosure compliance.
Tell us your category, budget range, and timing. We will take it from there.| Area | Global tendency | Japan now | Evidence | What changes in a 2027 Japan plan |
|---|---|---|---|---|
| How creators are contracted | Most brands run programs in-house | Most commercial creators work through talent agencies | 66.3% of benchmark respondents run programs fully in-house (Influencer Marketing Hub, 2026); Japan column from our own work | Ambassador deals are agency contracts; budget time for negotiation |
| Disclosure liability | US FTC guidance also makes influencers responsible for disclosing | The advertiser alone is regulated | CAA stealth marketing rule, in force 1 October 2023 | Disclosure checks sit on the brand’s side of every approval |
| Path to purchase | AI tools and search send growing traffic to retailers | Buyers verify on search engines and retail sites before paying | 46.76% of Instagram and 44.75% of TikTok buyers searched on a search engine before buying (hotice, 2026) | Branded search and product pages are part of the campaign |
| Platform mix | X used by 21% of US adults (Pew, 2025) | LINE 92.9%, X 44.7% of people aged 13 to 79 | MIC FY2025 survey | Plan for LINE as the retention channel and X as a real-time channel |
On speed, we claim no fixed lag. The one direct comparison is generative AI: Japan (58.8%) trails the United States and Germany (75.6%), yet use among Japanese adults roughly doubled in a year. As a tendency, Japan moves the same way, later.
Talent Agencies Still Sit Between You and the Creator
In our experience, Japanese creators with commercial reach are usually managed by talent agencies or creator management companies, and commercial work is negotiated through them. That has not changed, and it is why Trend 4 looks different here: a year-long relationship with a Japanese creator is a year-long contract with their agency, covering exclusivity, usage rights and scheduling as well as the posts. Our guide on how to discover influencers covers how to approach them. What to change: start ambassador negotiations a quarter earlier than you would at home.
The Advertiser Carries the Disclosure Liability
This is Trend 7 in its Japanese form. Japan’s stealth marketing rule regulates the advertiser, not the creator, so a missing “PR” label is the brand’s legal problem even when the creator made the mistake. Our guide to Japan’s stealth marketing regulation explains the labelling requirements.
Japanese Buyers Verify Before They Purchase
Few Japanese buyers purchase straight from a post. In our surveys, 46.76% of Instagram buyers searched for the product on a search engine and 40.05% checked the official site or a major retailer; only 16.44% bought on the spot. TikTok buyers showed the same pattern, at 44.75%, 39.50% and 18.25%. This is why Trend 6 matters more in Japan: results often land in search and retail data, not clicks. Our guide to social media in Japan covers where people check, and our statistics page has the wider numbers.
A Different Platform Mix: LINE and X
Japan’s platform mix is not the American one. In the MIC FY2025 survey of people aged 13 to 79, 92.9% used LINE, 81.5% YouTube, 54.8% Instagram, 44.7% X and 36.7% TikTok. X is far stronger than in the United States (21% of adults, per Pew) and works as a real-time channel for news, trends and fandoms. LINE is where customer relationships continue after a first purchase. So Trend 2 plays out in Japan on Instagram, TikTok and X, while LINE carries retention. See our guides to social media in Japan and LINE marketing in Japan.
What Is Not Changing
Three things hold steady in 2027: audience fit, slow-built relationships and creative quality. When someone asks you to “do something new”, these are the counterweight.
Fit Still Beats Follower Count
A creator whose audience matches your buyer usually outperforms a larger creator whose audience does not, and no platform change alters that. The check that matters most for Japan is the audience country breakdown. Some well-known Japanese creators, particularly in anime, fashion and travel, have a large share of followers outside Japan, so a big account can deliver little reach among Japanese buyers. Ask for the breakdown before you shortlist anyone.
Relationships Still Take Time to Build
Trust builds over several projects, and in Japan with the agency as well as the creator. Agencies remember which brands briefed clearly, paid on time and respected their talent’s judgement, and that record shapes which creators they offer next time. The move to year-long ambassadors (Trend 4) partly reflects this. A brand that changes its creator list every quarter restarts the process every quarter.
Creative Quality Still Decides the Outcome
Formats change, but a clear, credible post still beats a weak one. In our Instagram purchasing survey, the most-cited deciding factor, at 37.50%, was a creator talking honestly about a product’s drawbacks. Posts that sound like adverts tend to lose attention in Japan, so give creators room to say what they actually think.
What to Put in Your 2027 Plan
The nine trends as a quarterly plan for Japan, ready to forward.
| Quarter | Try | Stop | Measure |
|---|---|---|---|
| Q1 | Rewrite key product pages with tables, sources and question-style headings (Trend 1) | Buying one-off posts from creators you would want all year | Baseline branded search and saves |
| Q2 | Sign one or two ambassadors on annual terms through their agencies (Trend 4) | Contracts that leave paid usage undefined | Content quality and engagement across repeat posts |
| Q3 | Run the best creator posts as paid ads, and pilot a nano program (Trends 5 and 8) | Judging creator work on clicks alone | Branded search lift and retail sales against the Q1 baseline |
| Q4 | Pair short creator clips with longer reviews or livestreams for the year-end season (Trend 3) | Posting without a disclosure check on reused content | Which creators to renew for 2028 |
On budget, decide before the year starts how much goes to new approaches and how much to what already works, and write the test share down so it is not cut in the first bad month. The right size depends on three things: how proven your current Japanese program is, how long your product’s purchase cycle is, and whether you can measure the test against a baseline. Our breakdown of influencer marketing costs in Japan gives reference rates for creator fees, usage rights and agency costs.
If this plan raises the question of who should run it for you in Japan, our comparison of influencer marketing agencies in Japan covers what to ask before you sign.
FAQ
What are the biggest influencer marketing trends for 2027?
The three with the widest impact are AI search becoming a discovery channel, the move from one-off posts to year-long ambassadors, and stricter enforcement of disclosure rules. AI tools already send fast-growing traffic to US retailers, which changes how brands get found. Ongoing creator programs are now the norm among brands surveyed, which changes how creators are contracted. And regulators in Japan and the United States are issuing orders and warnings, which changes what brands are exposed to. The table at the top lists all nine.
Is influencer marketing still growing?
Yes, in Japan and in the United States, the two markets with the clearest data. CyberBuzz and Digital InFact forecast that Japan’s influencer marketing market will roughly double between 2024 and 2029, and the IAB projected that US creator ad spend would grow 26% in 2025, about four times faster than the media industry overall. Spending is also shifting toward paid use of creator content and always-on programs. For market size by year and the sources behind each figure, see our influencer marketing statistics for Japan.
How is AI changing influencer marketing?
The biggest change is in discovery. AI assistants and AI search now answer product questions directly, so fewer people click through to websites and more of the first impression is formed by what the AI quotes. Adobe measured a 693.4% rise in generative AI traffic to US retail sites in the 2025 holiday season, and Google has offered AI Mode in Japanese since September 2025. For brands, creator content and product pages become source material, so clear data, named sources and question-style headings matter more. See Trend 1 above.
Are influencer marketing costs going up?
Our cost guide gives reference rates; the trend is in the cost drivers, because brands are now buying more than posts. Paid usage of creator content, longer usage periods and year-long ambassador contracts with exclusivity each add to the fee, and in Japan those terms are negotiated with the creator’s agency. Nano programs add operational costs such as shipping, samples and contract management. Budget for these items explicitly rather than assuming the post fee covers them. Our breakdown of influencer marketing costs in Japan gives reference rates and explains what drives each element.
What is different about influencer marketing in Japan?
Four things. Most commercial creators are managed by talent agencies, so deals are made through them. The advertiser alone carries legal responsibility for disclosure under the stealth marketing rule. Japanese buyers verify before they buy, with 46.76% of Instagram buyers in our survey searching for the product on a search engine. And the platform mix differs: LINE reaches 92.9% of people aged 13 to 79 and X is much stronger than in the United States. Our guide to social media in Japan covers the platforms.
Should brands move to long-term ambassador deals?
Yes for products people buy repeatedly or consider for a long time, such as beauty, food, gadgets and subscriptions, provided you can commit budget for at least a year. For a one-time launch, a seasonal product or a first test in Japan, start with a few short campaigns, pick the creators whose content performs, and move those to annual terms. In Japan, expect the ambassador contract to be with the creator’s agency. See our guide to influencer contracts in Japan.
Will virtual influencers replace human creators?
Not on current evidence. Our forecast is that brands will use them alongside human creators, not instead of them. Virtual characters suit always-on brand presence and controlled messaging, while human creators remain essential for reviews and first-hand use, which Japanese buyers look for before purchasing. In our survey of 149 Japanese social media users, most had no strong view about influencers using AI-generated content, but 19.1% said it made them distrust the influencer. If you use a virtual influencer, label it clearly. Our guide to VTuber marketing in Japan covers the performer-led alternative.
Methodology and Data Sources
hotice survey figures come from reports on hoticeglobal.com; the Instagram usage survey was fielded in January 2026, and the other reports do not state fieldwork dates or sampling methods. Sources were last checked on 25 September 2026. This article is updated every October, and a forecast that turns out wrong will be marked as missed here, not deleted.
| Figure | Source | As of |
|---|---|---|
| Generative AI retail traffic | Adobe | 1 November to 31 December 2025 |
| Clicks with and without AI summaries | Pew Research Center | March 2025 |
| AI Mode in Japanese | Google Japan Blog | 9 September 2025 |
| Generative AI use by country | MIC 2026 White Paper summary | Fielded January to February 2026 |
| Platform usage rates in Japan | MIC FY2025 media usage survey | Fielded December 2025 |
| US platform usage | Pew Research Center | February to June 2025 |
| Japan video and social ad spend | Dentsu, internet ad analysis (CARTA Holdings, Dentsu, Dentsu Digital, Septeni) | 2025, published 5 March 2026 |
| Japan influencer and vertical video market | CyberBuzz and Digital InFact | Published 7 November 2024 |
| Shorts daily views | YouTube CEO letter | 21 January 2026 |
| Always-on, paid use, measurement | Medill Spiegel Research Center | Fielded June 2026 |
| Partnership ads run rate | Meta Q1 2026 earnings call | 29 April 2026 |
| US creator ad spend | IAB | Published 20 November 2025 |
| Creator tiers, in-house share | Influencer Marketing Hub | Published May 2026 |
| Third-party cookies | WebKit, Google Privacy Sandbox | March 2020; 22 April 2025 |
| External transmission rules | MIC | In force 16 June 2023 |
| Stealth marketing rule and enforcement | CAA, CAA enforcement summary | In force 1 October 2023; summary to 31 July 2026 |
| FTC review rule, warning letters and influencer guidance | FTC, FTC warning letters, FTC Disclosures 101 | Rule in effect 21 October 2024; letters 22 December 2025 |
| EU influencer sweep | European Commission | 14 February 2024 |
| VTuber market | Yano Research Institute | Published April 2025 |
| hotice surveys | Instagram usage (n=534), Instagram purchasing (n=636), TikTok usage (n=528), TikTok purchasing (n=631), AI-generated content (n=149) | September 2025 to February 2026 |
Update history: first edition, September 2026.
Supervised by the hotice Editorial Team, specialists in helping global brands enter the Japanese and Asian markets through influencer marketing. Last updated: September 2026.
Pricing, past campaigns, and how contracts and ad-disclosure compliance are handled from start to finish. Ask us anything before you commit to a budget.
Overseas brands welcome. We work in English, Japanese, Chinese, and Korean.